California Smoke Damage Act Sets Claim, Testing and Repair Standards
AB 1795 presumes wildfire-area smoke damage is wildfire-related and sets requirements for testing, temporary living benefits and restoration.
California’s Smoke Damage Recovery Act changes how smoke-related property claims are investigated and handled. Signed by Gov. Gavin Newsom, Assembly Bill 1795 creates a presumption that smoke damage inside a wildfire impact area resulted from the wildfire and sets requirements for testing, claim handling and home restoration.
For property owners, the change addresses a recurring dispute: whether smoke has damaged a home, what testing is needed to assess it, and what work will return the property to a safe condition. For insurers and claims professionals, the law sets expectations across the process, from inspection timelines to repair estimates and adjuster training.
What the new presumption means
AB 1795 establishes that smoke damage within a wildfire impact area is presumed to have resulted from that wildfire. The presumption gives claims a defined starting point when the connection between a fire and smoke effects is at issue. The article does not specify how an impact area will be identified or describe what evidence may rebut the presumption, so those details remain important to the law’s practical application.
The act also requires insurers to pay for necessary testing and sampling. That requirement puts assessment costs within the claims framework rather than leaving homeowners to resolve them without support. Testing can be central to determining the extent of contamination and what remediation is needed; the source does not spell out specific testing methods or thresholds.
Insurers are also barred from ending Additional Living Expense benefits until a home has been restored and is safe to occupy. ALE coverage generally helps with additional living costs when a covered loss makes a home unfit for use, subject to the terms of the policy. Under the act’s stated requirement, the benefit cannot be terminated before both restoration and safe occupancy are reached. The source gives no separate payment limits or eligibility rules, so policy terms still matter for those details.
Requirements reach beyond testing
The law establishes timelines for inspections and claim handling, though the source does not give the specific deadlines. That distinction matters: the act sets a requirement for timely action, while the time frames themselves will shape how quickly inspections and decisions must occur.
Repair estimates must account for restoring homes to their pre-loss condition while meeting health and safety standards. This links the scope of repair work to both the property’s condition before the loss and the safety of the restored home. It also makes the quality and documentation of estimates consequential for both sides of a claim.
Policyholders retain the right to choose their restoration contractors. The act also sets training requirements for adjusters who handle smoke damage claims and includes protections for workers carrying out restoration and remediation. Together, those measures address several points where a smoke claim can become difficult: evaluating damage, deciding on the work, selecting who performs it and protecting people doing the cleanup.
For claims teams, the practical task will be translating these requirements into consistent procedures. Inspection records, sampling results, repair estimates and communications about whether a home is safe to occupy will all matter in showing how a claim has progressed. Policyholders, meanwhile, can keep copies of claim correspondence, testing information and restoration documents, and ask how decisions about occupancy and ALE benefits relate to the condition of the home and their policy.
Why the measure followed smoke disputes
The legislation followed concerns about a consumer protection gap raised by wildfire survivors, consumer advocates, public health experts and legislators. Smoke damage claims had become a point of contention between some insurers and consumers after the Los Angeles-area wildfires in June. Insurance Commissioner Ricardo Lara created the Smoke Claims and Remediation Task Force, which found that wildfire victims were encountering gaps in rules for smoke inspections, testing and restoration.
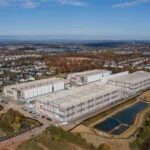
The act also responds to concerns raised after a June fire at a Lineage Logistics warehouse in Boyle Heights. The 491,000-square-foot cold-storage building fire sent large plumes of dark smoke into the air, affecting Boyle Heights and surrounding areas. Prolonged smoke impacts prompted questions about insurance coverage, illustrating that smoke-related concerns can extend beyond the structure where a fire begins.
AB 1795 directs the California Department of Insurance and CalOES to assess challenges associated with smoke damage and develop recommendations to strengthen protections for property insurance consumers and communities affected by future contamination events. That work may help clarify how the new requirements operate in practice, but the source does not provide a timetable for the recommendations.
Industry response and what to watch
The American Property Casualty Insurance Association called the measure “a meaningful step toward clearer guidance on smoke damage claims.” The association also said that any rules developed around the changes should rest on credible science, valid methods and strong technical expertise. It said it would work with policymakers, insurers, consumers and scientific experts on standards intended to protect consumers, improve transparency and understanding, and support affordable and available coverage for Californians.
That response points to the key implementation question: how the broad requirements will be applied to individual claims. Clear approaches to testing, inspection, restoration and safe occupancy could help reduce disagreement over what a smoke-damaged home needs. The act establishes the framework; the details of its application will determine how consistently policyholders and insurers can navigate a smoke claim.


