Blood and Tissue Therapies Put New Focus on Liability and Insurance
Blood-shield protections vary by state and don’t remove contamination or operational risks. Insurers are weighing companies’ quality controls and response plans.
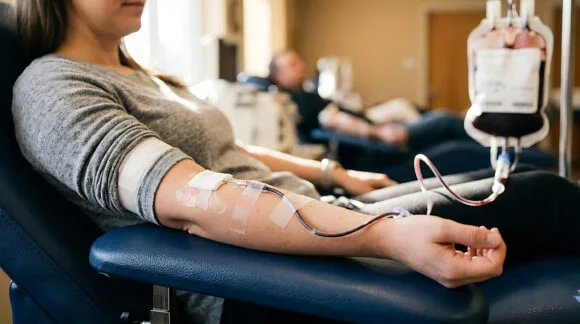
Blood- and tissue-based therapies are expanding the life sciences market, and with that growth comes a harder insurance question: how much protection do blood-shield statutes provide when a biological product causes harm? These statutes have long shaped liability for blood banks, hospitals and other organizations, but many were written around transfusions. Their application to newer therapies may be less clear.
For insurers and companies, the practical point is that statutory protection is only one part of the risk picture. A firm’s handling of biological materials, documentation, contracts and ability to respond to an adverse event can all affect its exposure and how underwriters assess it.
Protections vary, and their reach has limits
Blood-shield statutes generally treat the provision of blood and certain human tissues as a medical service rather than a product sale. That distinction can help limit some strict product-liability claims against organizations that collect, process or distribute those materials. Many states adopted this approach after mid-20th-century disputes over liability for transfusions.
The details differ across states, including which materials and organizations are covered. The statutes also arose before today’s range of biologic medicines and regenerative treatments. As biological materials take on new uses, companies and insurers must consider whether a particular product and process fit within protections developed for an earlier form of care.
Even when a statute applies, it doesn’t prevent lawsuits over alleged contamination, inadequate screening, disease transmission, negligence or operational failures. A company may ultimately prevail, yet still incur substantial costs to defend a claim. That leaves insurers looking closely at how a business manages its work, rather than relying on a statutory defense alone.
Underwriting follows the material through the supply chain
Risk assessment can start with collection and continue through testing, storage, transport and distribution. Each stage brings its own opportunity for error, and biological materials may require specific environmental conditions to preserve their integrity. Weak inventory controls or a lapse during transport can undermine safeguards put in place earlier.
Collection practices matter, too. Sterile recovery methods, clear procedures and trained staff help reduce the chance that a problem enters the supply chain at the outset. Insurers want to understand how organizations manage these steps and what happens when results or events point to a possible safety issue.
Contamination is a leading concern, but donor screening is only one layer of prevention. Medical-history reviews and disease testing can help identify risks before materials are used. Testing and quarantine procedures can keep suspect material out of circulation while results are assessed. Records showing what was done, when and by whom can also help establish whether procedures were followed if a claim arises.
Quality-management programs give underwriters another view of a company’s approach. Regular audits, documented processes and reviews of operational gaps can help identify weaknesses before they lead to patient harm or a costly claim. These controls may indicate how consistently an organization manages risk across its operations.
Contracts and response plans matter
Consent forms and service agreements can help clarify the nature of the relationship and support the position that an organization is providing a medical service. Their wording may need to reflect the requirements that apply in each state, since blood-shield protections are not uniform. Companies entering this field should understand how their contracts fit their operations and where their activities take place.
Preparation for an adverse event is another part of the risk review. Companies need ways to trace materials, identify potentially affected patients or batches, and carry out a recall when warranted. Response plans may also include required reporting and an investigation to identify the cause of an incident.
A quick, organized response can help limit further patient harm and clarify what happened. For underwriters, the ability to trace materials and act on a problem can signal how prepared a company is to manage a serious event. That preparation also depends on maintaining reliable records across the supply chain.
Specialized guidance as therapies expand
Biotechnology and medical-product companies entering this market may be encountering these questions for the first time. Some may assume statutory protections cover more of their activities than they do; others may not yet have mapped biological-material risks to their insurance program. Brokers and underwriters with life sciences experience can help assess potential coverage gaps, state-specific differences and the connection between a company’s operations and its insurance needs.
The growth of biologics and regenerative medicine is likely to keep the scope of blood-shield protections under scrutiny. For companies, the clearest takeaway is operational: build careful screening, testing, storage, transport and documentation practices into the process, and keep response plans ready. Insurance planning works best when it reflects how materials actually move from collection to patient use.


